Category: Zoho Books, ERP & Finance Operations Author: AorBorC Technologies Published: September 17, 2026
HMRC says it will sign up, in stages from September, people its records indicate should already be using Making Tax Digital for Income Tax. That changes an account status. A completed sign-up does not establish whether every relevant self-employment and property income source is represented, the right software is authorised, records are complete from the start of the tax year, or somebody owns the review before submission.
HMRC can complete the sign-up. It cannot connect the systems behind the numbers.
That distinction matters because a quarterly deadline can look like a filing task when the real work sits across sales, property records, expenses, bank feeds, e-commerce payouts, bookkeeping, permissions, and exceptions.
This is systems and workflow guidance, not tax advice. Use HMRC guidance and a qualified tax adviser to decide whether the rules apply, whether an exemption is available, and how a particular transaction should be treated.
What HMRC said on September 17
HMRC's Agent Update 147 gives two practical signals. The second quarterly update deadline for the 2026–27 tax year is 7 November 2026. It also says HMRC will begin staged sign-ups from September for people who should be using Making Tax Digital for Income Tax but had not signed up, with confirmation sent afterward.
This is an operational reminder, not a new regime announced on September 17. The important change for teams is that waiting for sign-up to be somebody else's project is no longer a safe operating assumption. HMRC may set the account state using information it already holds. The taxpayer or agent still has to confirm current income sources and complete the rest of the setup.
Who the 2026–27 requirement applies to
For 2026–27, HMRC says the requirement applies from 6 April 2026 to a sole trader or landlord registered for Self Assessment who had qualifying income over £50,000 in 2024–25 and is not exempt.
"Qualifying income" is not profit after costs. HMRC defines it as gross income before expenses from self-employment and property, potentially across several sources. Employment pay and dividends do not count toward that threshold, although they may belong on the tax return.
HMRC may use the 2024–25 return and, if it was submitted before sign-up, information from the 2025–26 return when asking the person to confirm their records. New, changed, or ceased sources can make that picture incomplete. If all relevant sources ceased before 6 April 2026, HMRC provides a route to update the record; later cessation may still require MTD steps. Settle that tax position with HMRC or an adviser rather than guessing through a software setting.
Sign-up is an account state, not a working record chain
After sign-up, HMRC's own guidance still tells the taxpayer or agent to access the service, check income sources, choose software that covers those sources, authorise it, create or catch up digital records, send overdue quarterly summaries, and eventually submit the tax return.
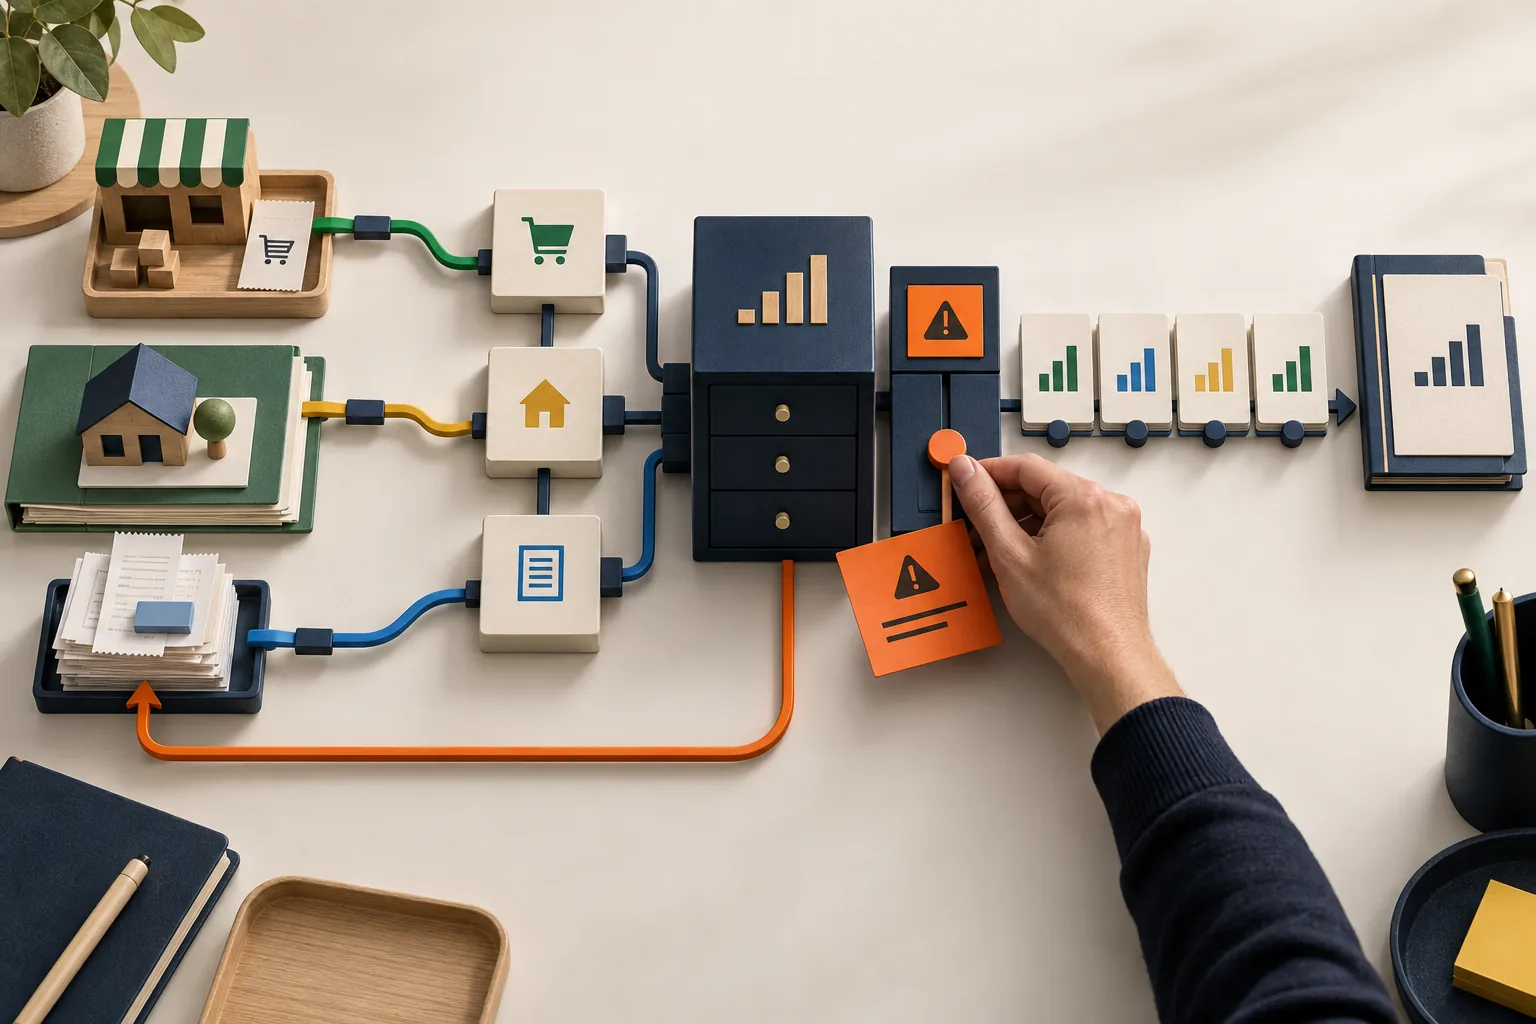
AorBorC uses digital record chain as an operational model for that work. It is not an HMRC legal term. It shows where a transaction starts, how it becomes an accounting record, who reviews exceptions, and how totals reach a quarterly update and tax return.
A completed sign-up status therefore proves little about readiness. It does not prove that a landlord's UK and overseas property sources match HMRC's record, that a sole trader's refunds and payment fees reach the ledger correctly, or that the person preparing an update is allowed to send it.
Separate the legal duties from implementation controls
HMRC guidance requires keeping the relevant digital records, using compatible software, maintaining digital links where relevant records move between products, sending quarterly updates, and submitting the tax return. Quarterly updates are summaries of income and expenses, not tax returns.
For 2026–27, HMRC says missed quarterly update deadlines do not attract penalty points. That does not remove the duty to keep digital records or send the updates before the tax return. The annual tax-return and payment deadline still matters, as do the applicable late-return, late-payment, and interest rules.
Operational controls are safeguards a team chooses so the records are trustworthy: a named owner, source-to-ledger reconciliation, an unmatched-entry queue, separate prepare/review/send permissions, a connection-expiry alert, and test evidence. These controls are not extra HMRC rules. They prevent a filing deadline from becoming the first end-to-end test.
Digital links do not mean API-only automation
HMRC says that when more than one product is used to keep the relevant digital records and make submissions, those records need a digital link. Permitted methods include linked spreadsheet cells, imported spreadsheets, portable transfers, XML or CSV files, automated transfer, and APIs. After a digital record has been sent in a quarterly update, it must not be moved manually by re-entering or writing it out, or by cut-and-paste or copy-and-paste.
The scope is equally important. HMRC says software used only for bookings or a till that records sales receipts does not itself need to be digitally linked if it is not used to create the MTD records. So "connect everything" is not a useful compliance slogan.
There can still be a strong operational reason to connect or reconcile upstream systems. If Shopify, a marketplace, POS, property platform, or ERP feeds the accounting records, someone should be able to explain how orders, refunds, fees, settlements, inventory-related costs, and bank receipts become the totals under review. That is a control decision. Whether a particular system falls inside the legal digital-link requirement depends on how it is actually used.
Zoho Books must cover the relevant income sources
Zoho documents HMRC connection, obligation retrieval, quarterly submissions, role permissions, and an activity log in Zoho Books. It documents a combined View and Generate permission, separate Send and Export permissions, and view/manage permissions for settings and agent invitations. The connection is valid for up to 18 months, but account changes can invalidate it sooner.
Those features do not make product fit automatic. Zoho currently documents support for sole traders, and landlords with UK property; it says foreign property income is not supported. A person with both self-employment and UK property income can map both within one eligible organisation, but the sources the software must cover still need checking.
The question is not "Does the product have an MTD feature?" It is "Can the configuration cover every relevant source and period, preserve the records, separate duties, and give the reviewer enough evidence?" That is where Zoho finance and ERP workflow design and integration engineering should meet the accountant's tax interpretation.
A ten-step MTD record-chain checklist
- Step 01 — Confirm scope. Ask the taxpayer or adviser to document the Self Assessment status, 2024–25 qualifying-income calculation, exemption position, and any ceased sources. Do not infer scope from a letter alone.
- Step 02 — Compare source records. Match HMRC's listed self-employment, UK property, and overseas property sources to current circumstances, including sources opened or closed since the last return.
- Step 03 — Map periods and obligations. Record the accounting period, quarterly update periods, actual deadlines, and tax-return path. Treat 7 November as the second quarterly deadline, not a sign-up deadline.
- Step 04 — Prove software coverage. Verify that the selected product and plan cover every relevant income source and filing step. Record any gap—especially foreign property—before configuration begins.
- Step 05 — Assign authorisations. Name the owner for the HMRC account, agent relationship, software connection, and reconnection. Store the approval status and an alert for connection expiry without storing credentials in a shared checklist.
- Step 06 — Draw the record path. Show where income and expenses originate, which product creates the MTD record, every permitted digital transfer, and where a human correction can occur.
- Step 07 — Control access and review. Grant the documented View and Generate, Send, Export, settings, and agent-invitation permissions only as needed. Add a procedural independent review where practical; for a sole operator, use an accountant or bookkeeper review, visible audit history, or another proportionate control.
- Step 08 — Catch up the records. Create or import the required records from the correct start of the tax year, address overdue quarterly updates, and retain original records, supporting documents, or copies in line with HMRC and adviser requirements.
- Step 09 — Reconcile before submission. Compare source-system totals, refunds, fees, settlements, bank activity, and accounting categories. Put unmatched items in an owned exception queue rather than forcing a balancing entry.
- Step 10 — Rehearse the whole cycle safely. Rehearse preparation, review, correction, evidence, and the tax-return handoff offline. Validate the submission path only through approved testing or with authorised live figures.
Risks, limits, and where the hype is not useful
The first risk is confusing a government account event with a completed process. The second is buying software before mapping the sources. The third is over-automating weakness: fast transfers do not correct duplicate orders, missing refunds, misclassified property costs, or an expired authorisation.
The opposite mistake is also common. A team can dismiss the first-year quarterly penalty position as permission to delay. That merely pushes unresolved records and overdue updates closer to the tax return, when there is less room to investigate exceptions.
AI can help classify documents or flag unusual entries, but it should not silently decide eligibility, exemptions, tax treatment, or questionable reconciliations. Use visible evidence and human review. The objective is a record chain that responsible people can inspect and operate.
Where AorBorC fits
AorBorC designs and repairs the operational layer around Zoho and connected systems: source mapping, Zoho Books configuration, roles, integrations, exception workflows, reconciliation, test evidence, and owner handoffs. For commerce-led sole traders, that can include e-commerce orders, refunds, payment settlements, and finance records. ERP modules, approvals, and reporting may support—but are not—the statutory submission.
The engagement is founder-led and human-reviewed. The AorBorC company profile explains that delivery model. We work with the client's accountant or tax adviser on the tax position; our role is to make the approved operating design dependable, supportable, and clear enough to audit or rescue later.
Business takeaway
Registration answers one question: is the person enrolled? Readiness asks whether the right sources and records are complete, software covers them, transfers preserve them, exceptions reconcile, and a named reviewer controls submission.
The practical move is to treat the 7 November checkpoint as a record-chain review, not a calendar reminder. Fix the earliest weak handoff first. Better data at the start is more valuable than a hurried correction at the end.
Your next move
If HMRC has signed you up—or your team is still preparing—run the ten checks with the taxpayer, bookkeeper, accountant, and system owner, as applicable. Leave with named owners, evidence requests, open exceptions, and a dated rehearsal.
If the record path crosses Zoho Books, commerce platforms, bank feeds, spreadsheets, or custom systems, plan the workflow with AorBorC. We can assess handoffs and turn the agreed finance process into an implementation or rescue plan.